

Insurance Adjuster Tactics After an Oklahoma Crash
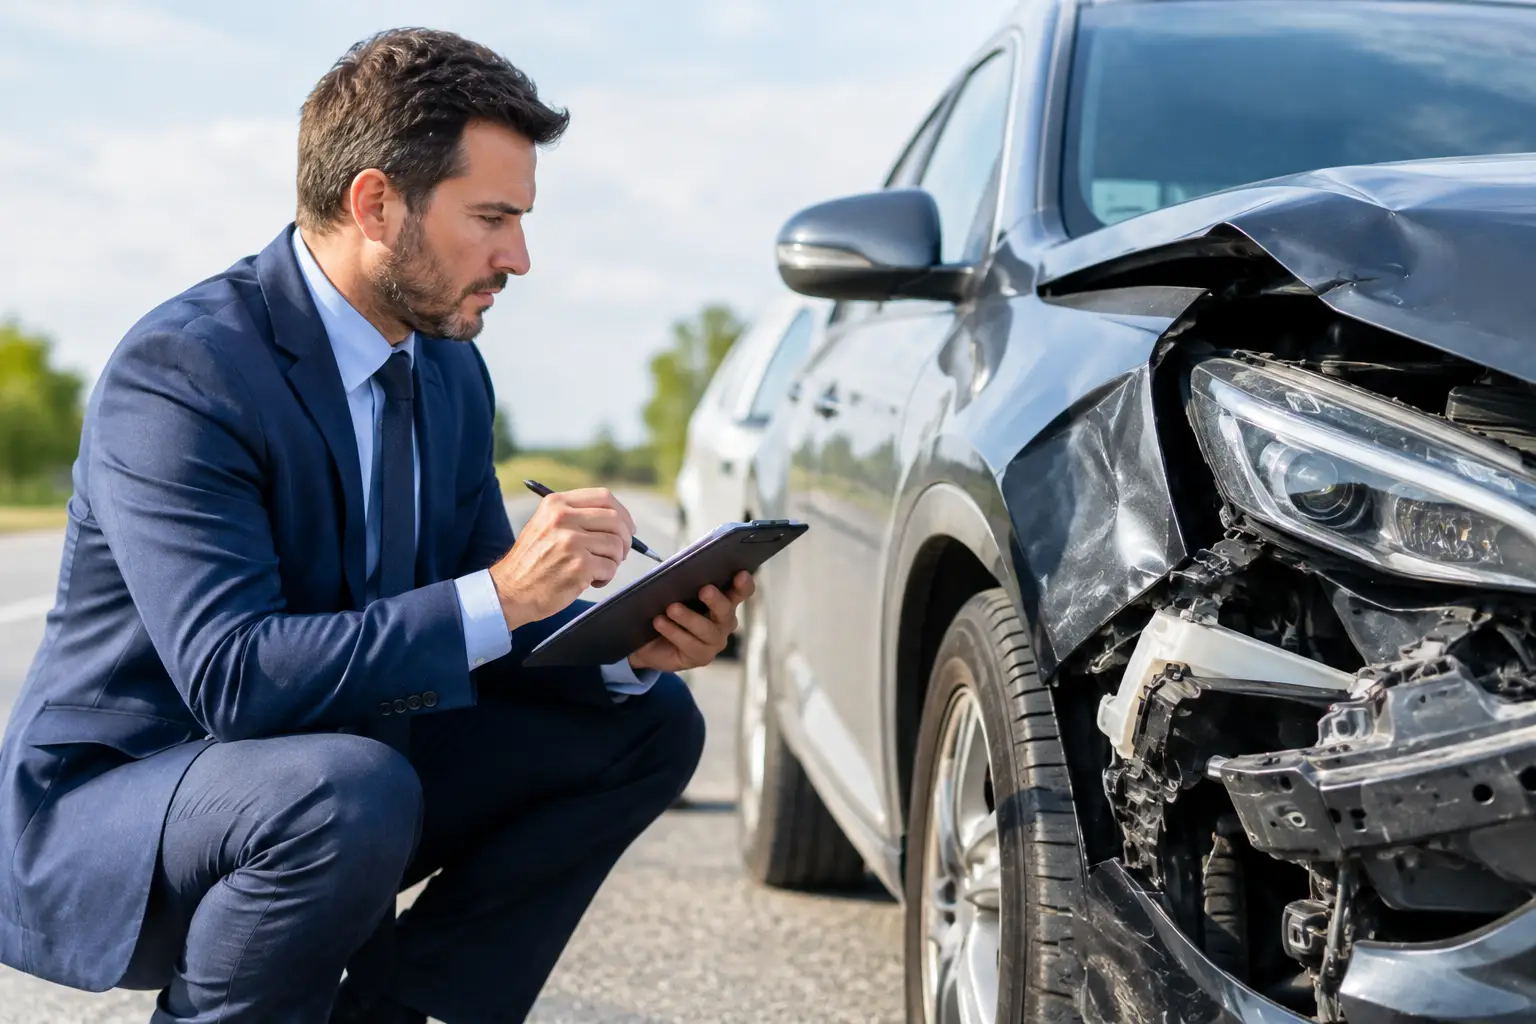
The phone call may come while your vehicle is still in the repair shop, while you are waiting on an MRI, or while you are trying to arrange a ride to work. The adjuster may sound concerned and helpful. But insurance adjuster tactics are designed to protect the insurer’s bottom line, not to make sure an injured Oklahoma family has what it needs to recover.
That does not mean every adjuster is dishonest or every early offer is automatically unfair. It does mean you should be careful. A serious collision, work injury, fall, or other accident can create expenses and limitations that are not clear in the first few days. Before accepting money, signing paperwork, or giving a recorded statement, understand what may be at stake.
Why Insurance Adjuster Tactics Matter
Insurance companies handle claims as a business. Their representatives are trained to collect information, assess risk, and resolve claims efficiently. In many cases, that includes looking for reasons to limit what the company pays.
For an injured person, the pressure can be immediate. Medical bills arrive. Missed paychecks create stress. A damaged car makes it hard to get children to school or get to medical appointments. An offer of quick money can feel like relief.
The problem is that a settlement usually requires a release. Once you sign it, you generally cannot return for more compensation if your back pain worsens, surgery becomes necessary, or you learn that you cannot return to the same type of work. The true cost of an injury may take weeks or months to understand.
Common Insurance Adjuster Tactics to Watch For
A fast settlement before you know the full extent of your injuries
An early settlement offer is often presented as a simple way to put the matter behind you. Sometimes a prompt offer is reasonable, particularly when property damage is the only issue. But when you have physical injuries, speed can work against you.
Soft-tissue injuries, concussions, spinal injuries, and joint damage do not always reveal their full impact at the emergency room. You may initially expect to feel better in a few days, only to need physical therapy, specialist care, time away from work, or help at home. A fair evaluation should account for both current losses and reasonably expected future needs.
Asking for a recorded statement right away
Adjusters frequently ask claimants to give a recorded statement. They may describe it as routine or say it will help move the claim forward. You are not obligated to handle a recorded statement casually, especially before you understand your injuries or have had a chance to review the facts.
A person in pain may guess at distances, speeds, timing, or symptoms. An innocent statement such as “I’m okay” can later be used to suggest you were not seriously hurt. If you do provide information, stay truthful, stick to facts you know, and do not speculate. A lawyer can help determine whether a recorded statement is appropriate and prepare you for it.
Looking for language that shifts blame
Oklahoma follows a modified comparative negligence rule. In general, your compensation may be reduced by your percentage of fault, and recovery can be barred if you are found more than 50 percent responsible. Because fault matters, an insurer may closely examine anything that could be framed as shared responsibility.
This can include a distracted-driving allegation, a question about whether you were speeding, a claim that you had time to avoid the crash, or an argument that you made an injury worse. Facts matter, and not every claim is one-sided. Still, do not assume the other driver’s insurer has already reached a fair conclusion simply because an adjuster says you “may have contributed” to the accident.
Treating a preexisting condition as the whole explanation
Many Oklahomans have prior back pain, arthritis, old sports injuries, or previous accidents. Having a medical history does not give a negligent driver or insurer a free pass for making your condition worse.
Insurers may review prior records and argue that your current symptoms existed before the accident. The real question is often more specific: Did the event cause a new injury, aggravate an old condition, or create new limitations? Your treatment records, prior medical history, work history, and the opinions of qualified medical providers can all be relevant.
Requesting broad access to your medical records
An insurer may ask you to sign a medical authorization. Some authorizations are written broadly enough to permit a search through years of unrelated medical information. That information can be used to challenge your claim, even if it has little connection to the injury at issue.
Medical documentation is necessary in many injury claims, but the request should be reasonably tailored. Before signing an authorization, understand what records it covers, who can receive them, and why they are needed.
Delaying while financial pressure builds
Not every delay is deliberate. Claims can take time when liability is disputed, multiple vehicles are involved, treatment is ongoing, or coverage questions need answers. But unnecessary delay can place real pressure on an injured person who needs a vehicle repaired or has bills piling up.
Keep records of every contact with the insurance company, including the adjuster’s name, the date, and what was discussed. Follow up in writing when possible. If delays continue or explanations keep changing, legal guidance can help bring structure and accountability to the process.
What You Can Do Before Speaking at Length With an Adjuster
Protecting your claim does not require being confrontational. It requires being deliberate. Get the other driver’s insurance information, obtain a copy of the crash report when available, and preserve photographs of the vehicles, scene, visible injuries, and property damage. If witnesses saw what happened, keep their names and contact information.
Seek medical care based on your symptoms and follow your provider’s recommendations. Gaps in care can occur for many understandable reasons, including cost, transportation, or family responsibilities. Still, insurers may point to a long gap and argue that you were not injured or that something else caused your condition. If you are unable to obtain recommended treatment, document why.
Keep a simple daily record as you recover. Note pain levels, missed work, trouble sleeping, medications, appointments, and activities you can no longer do normally. A medical chart may show diagnoses and treatment dates, but it may not fully capture that you cannot lift your child, finish a shift, mow the lawn, or sleep through the night.
Avoid posting about the accident or your activities on social media while a claim is pending. A photograph taken at a family gathering can be taken out of context and used to argue that your injuries are less serious than reported. Privacy settings help, but they are not a complete shield.
When a Lawyer Can Make a Difference
You may be able to resolve a straightforward property-damage claim on your own. But legal help becomes especially valuable when injuries are significant, fault is disputed, an insurer denies coverage, several parties may be responsible, or an offer does not reflect the losses you have suffered.
A personal injury attorney can investigate the accident, gather records, identify available insurance coverage, communicate with adjusters, and calculate damages beyond the first stack of bills. Depending on the facts, compensation may include medical expenses, lost income, reduced earning ability, pain and suffering, property damage, and other legally recognized losses.
For families dealing with a fatal accident, a workplace injury, a denied disability claim, or an insurer acting unfairly, the process can be even more complicated. Deadlines apply, evidence can disappear, and the language in an insurance policy can matter. Getting answers early can preserve options without forcing you to make a rushed decision.
Burton Law Group represents injured Oklahomans with the personal attention people deserve when an insurance company is asking them to settle their future for less than it may be worth.
You Do Not Have to Accept the First Story
An adjuster’s evaluation is not the final word on your injury, your pain, or your claim. Be honest, preserve what you can, and give yourself time to understand how the accident has affected your health, work, and family. A careful response today can help protect the choices you need tomorrow.